
Value machines dug China’s equipment niche – will electric turn it into leadership?
28 August 2026
Chinese equipment manufacturers are no longer knocking at the door of Western markets – they are already inside.
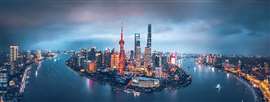 Chinese manufacturers learned quickly from the international OEMs that established factories and design centres there. Image: Adobe Stock
To put this in perspective, we looked back at how the construction industry has transformed multiple times over the years, either by technology changes, like improved hydraulics, or global factors like currency changes or supply chain advantages.
When Japan changed the game
Using data supplied by Off Highway Research (OHR), the first wave that was notable was in the 1990s when the Japanese entered global markets. The Yen was low versus the US dollar and European currencies, and they managed to build better excavators than any other global player.
They also taught everyone a lesson on manufacturing and supply chain efficiency. At its peak the Japanese manufacturing powerhouse ultimately achieved a 20-25% share of the markets in the EU and North America. They didn’t do this at the value end of the market – they achieved this with quality products firmly in the higher value mid and premium tier segments.
The next wave came from the Koreans. They had no real technology advantage, but leveraged the Japanese supply chain for excavators and combined that with a low labour cost and a currency advantage and built low-price products. After about 15 years the Koreans had seen their market share grow to about 6-7%.
The latest wave is coming from China – and it is already breaking across Western markets. Chinese manufacturers learned quickly from the international OEMs that established factories and design centres there to compete in a rapidly growing Chinese market, absorbing technologies and then developing them further in their own products.
At the same time, they built enormous production capacity, creating a powerful export engine whenever domestic demand fell short. Armed with increasingly capable machines at highly competitive prices, Chinese OEMs have gained market share at remarkable speed. They are already approaching the levels achieved by the Korean manufacturers – in less than half the time.
The value trap
The value portion of the market is a very competitive place. As many products are being commoditised, OEM’s can gain an advantage through pricing as long as local support is available. Both Korean and Chinese OEMs are primarily competing in this space, taking share from each other as they are focused on expanding their dealer networks to create an advantage.
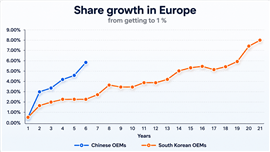
If they keep focused on this value segment, they each run the risk of stalling at 8-12% share of the market. Western and Japanese OEM’s will continue to innovate their products to stay ahead, losing potentially a lower margin part of the market to the Chinese and Koreans.
However, the Chinese OEM story is not finished. The next major shift in construction equipment could play more strongly to their strengths. China already has the industry’s broadest range of battery-electric equipment, backed by a domestic ecosystem developed at enormous scale through the automotive sector.
The parallels with the development of Japan’s hydraulic excavator supply chain are clear – once a country builds deep expertise, suppliers and manufacturing capability around a new technology, that advantage can take many years for competitors elsewhere to replicate.
The ace up China’s sleeve
Unlike the Japanese and Koreans before them, Chinese OEMs still have this ace to play – electrification. The question is no longer whether they can build the machines, but whether they can accelerate market adoption and bring operating costs down far enough to make electric equipment compelling at scale.
If they can, it could upend the established world order and change their global position entirely – propelling Chinese OEM market share towards 20% within the next decade.
Alan Berger and Robert Droogleever are part of consultancy firm abcg.
CONNECT WITH THE TEAM